
Demographics move slower than anything else in markets and reverse less often than everything else. A birth rate that fell twenty years ago has already determined how many people will enter the workforce next year, and no policy announced today can change it.
That combination (slow, large and close to irreversible) makes population structure one of the few genuinely long-horizon inputs available. It will not tell you anything about next week. It explains a great deal about why interest rates, currencies and entire sectors have behaved as they have over decades.
Why population structure reaches markets at all
Markets aggregate the decisions of people who work, spend, save, borrow, buy homes and pay taxes. Change the composition of the population and you change those decisions in bulk.
The most important variable is age structure, because consumption and saving follow a life cycle that is remarkably consistent across countries.
Young populations borrow and spend: education, housing, durable goods, family formation. They need infrastructure and job creation, and they consume more than they save.
Middle-aged populations are peak savers. Earnings are highest, the mortgage is being paid down, and retirement is close enough to plan for. This is the cohort that accumulates financial assets.
Older populations draw down. Healthcare, pharmaceuticals, home care and income-generating assets replace growth assets, and net saving turns negative.
The second variable is the dependency ratio, how many workers support each retiree. The spread is wide: Japan has about fifty people over sixty-five for every hundred of working age, India about eleven. When that ratio falls, the same tax base must fund more pensions and more healthcare, which pressures public finances directly and eventually shows up in government borrowing.
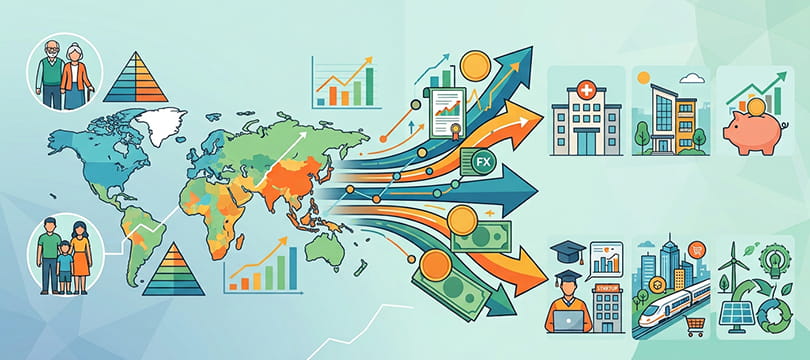
The four shifts already underway
Aging in mature economies. Rising longevity and falling birth rates are pushing up the share of the population over sixty-five across Europe, Japan, China, Korea and North America. This is not a projection; the people are already born.
Population growth concentrated in a few regions. The United Nations projects the global population to peak at around 10.3 billion in the mid-2080s, but the distribution is entirely uneven. Sub-Saharan Africa and parts of South Asia account for most of the growth, while several advanced economies and China are already shrinking.
Urbanization. The World Bank expects close to seven in ten people to live in urban areas by 2050. That requires housing, power distribution, transport, water and waste infrastructure at a scale that is largely unbuilt.
Migration. Wage differentials, conflict, instability and climate pressure keep roughly 300 million people living outside their country of birth (UN, 2024), and the flows partially offset labor shortages in aging economies while changing consumption patterns and remittance flows.
The macro consequences that matter to a trader
This is where the link between demographics and markets stops being a social science topic and becomes a trading one.
Real interest rates. A large cohort of peak savers pushes the supply of savings up relative to the demand for investment, which pushes down the equilibrium real rate. A substantial part of the decades-long decline in real yields across developed markets is attributable to the baby boom generation moving through its highest-saving years: Federal Reserve economists (Gagnon, Johannsen and López-Salido) put the demographic contribution at about one and a quarter percentage points of the fall in the equilibrium real rate since 1980. As that cohort retires and draws down, the same logic runs in reverse, which is the argument Charles Goodhart and Manoj Pradhan make in The Great Demographic Reversal (2020): the era of very low rates is structurally over.
Inflation. The direction is genuinely contested. One argument says an aging population is deflationary, because older people consume less. The other says it is inflationary, because a shrinking workforce supporting more retirees means fewer producers, more consumers, and upward pressure on wages. Japan supports the first reading; the post-pandemic labor shortages in several economies supported the second.
Public debt. Aging raises pension and healthcare spending as a share of output while narrowing the tax base. Governments face a choice between higher taxes, lower benefits and more borrowing, and historically they choose borrowing. That has consequences for sovereign bond supply and eventually for currencies.
Currencies. Japan is the case study, and it is worth understanding properly. Decades of aging and weak domestic demand produced persistent deflation, which produced near-zero interest rates, which made the yen the world's funding currency. An entire class of carry trades exists because of Japanese demographics. As Japanese yields rise enough to bring domestic capital home, that structure unwinds, and it is a demographic story expressed as a currency move. The two things to watch are the ten-year JGB yield, now near 3% for the first time since the 1990s, and the pace at which the Bank of Japan lets its bond holdings run off.
Sectors on each side of the shift
What follows is a description of structural demand, not a recommendation. Demographics change the size of a market; they say nothing about the valuation you are paying for it.
Aging supports healthcare, diagnostics, pharmaceuticals, medical devices, home care and residential facilities, plus remote monitoring, assistive robotics and financial services aimed at retirement income and wealth transfer.
A shrinking workforce supports automation, industrial robotics and software that substitutes for labor. When workers are scarce and expensive, capital investment that replaces them becomes economic in industries where it never was.
Emerging market growth supports infrastructure, telecommunications, digital payments, education, consumer goods, energy and banking: the sectors that build out when hundreds of millions of people enter the formal economy.
Urbanization supports construction, grid investment, public transport, water treatment, waste management and everything grouped under smart city technology.
Under pressure: peripheral real estate in shrinking regions, traditional retail, services aimed at children in low-birth-rate countries, and any business dependent on domestic demand in a contracting population. Public pension and health systems come under the same pressure, with tax and debt consequences.
Where the reasoning goes wrong
Demographics is a tailwind, not a return. A sector with guaranteed demand growth can still be a poor investment if the price already reflects it, the industry is over-supplied, or margins are competed away. Healthcare demand in aging societies is certain; healthcare equity returns are not.
The timescale is generational and markets are not. These trends play out over decades. A correct demographic thesis can underperform for ten years, which is longer than most people will hold a position.
The obvious conclusion is priced. Everyone can see the population pyramid. Any part of the story that is simply known is in the price, and the returns come from the parts that are misjudged, usually the pace, or the second-order effects rather than the first.
Decline creates opportunity too. A shrinking market rewards consolidation. Operators who buy competitors and take share in a contracting industry frequently do better than participants in a growing one where everyone is expanding capacity at once.
How to use it
Demographics is best used as a filter on other analysis rather than as a trade in itself.
It tells you which structural pressures a currency's economy is under, and therefore which way its policy is likely to lean over years. It tells you which sectors have wind behind them and which are pushing against it. And it explains persistent anomalies that look irrational on a shorter view: why Japanese rates stayed at zero for decades, why European growth expectations keep being revised down, why some emerging markets carry a growth premium that has nothing to do with their current data.
It does not time anything. The direction of the wind is not the same as which ship arrives first, and the market between here and there is decided by policy, valuation and events that no population projection contains.